Weekly Update
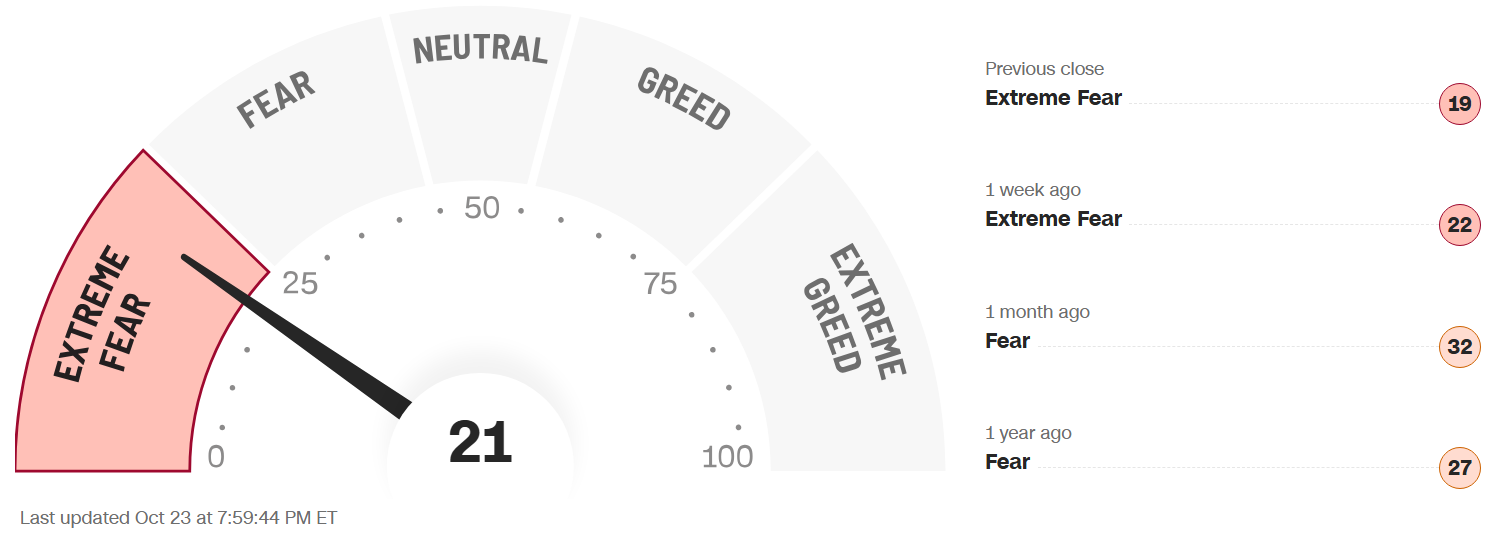
The Fear & Greed Index (found on cnn.com) is one of the easiest indicators to use to determine current market emotion. This simple to read gauge, highlighted in our publication When to Buy and When to Sell: Combining Easy Indicators, Charts, and Financial Astrology (available on Amazon), is measured in a range from 0-100, and currently reads 21 as of the close on Friday, October 23, 2026.
The gauge briefly bounced out of the Extreme Fear level earlier this week, however, settled back into the upper Extreme Fear level after market declines on Thursday and Friday, rising only 3 points from last week’s close of 18. This was reflected in the S&P 500, which dropped 37 points, from 7,660 to 7,623, as the back-and-forth price action continues. Remember, this level of fear often suggests a rally in the near future, which started and stalled this week, and the lower it falls the more likely a reactionary bounce is to occur.
The 7 internal factors used to formulate this gauge are listed on the screen (below):
Market Momentum – (S&P 500 vs its 125-day moving avg) = EXTREME FEAR
Stock Price Strength (# of new 52-week highs vs new 52-week lows) = EXTREME FEAR
Stock Price Breadth (# of shares rising vs falling on NYSE) = EXTREME FEAR
Market Volatility (measured by the VIX) = EXTREME FEAR
Put to Call Ratio 5-day avg. (# of Puts (bearish) vs Calls (bullish) = EXTREME FEAR
Safe-Haven Demand (which measures stocks vs bonds) = EXTREME FEAR
Junk Bond Demand (non-govt. bond yield spread) = FEAR
This week, 0 of these 7 factors changed levels, as overall momentum remained in Extreme Fear. For weeks we have expressed the fragile underlying structure of the markets in this seasonally weak period, an indicator of defensive positioning by institutions.
Market internals Moving Averages’ (MAs) bearish sentiment quietly showed some improvement, with a broader scope of stocks gaining. The longer-term 200-days (in an official “bear” market under 50%), are now at 44%, vs last week’s close of 41%, with the DJIA still leading at 70%, (vs 67% as week). The shorter-term MAs now read 38% on the 50-day (vs 28% last week), and 49% on the 20-day (vs 40% last week), as the only real weakness were chips and technology. Sector strength remained fragmented this week, as speculative stocks, which are interest-rate sensitive, remained low. Defensive sectors including Healthcare, Energy, and Utilities remained strong in the short-term, while Consumer and Communications continue to struggle. Earnings season is now in full gear, reporting mixed results thus far, and the weak will certainly be punished in this environment.
The “Risk-On” sentiment weakened a bit this week, as continued uncertainty regarding the military conflict, rising oil prices, and high inflation-related readings continue to control the market. 10-yr bond yields did decline, due to a Flight-to-Quality move into bonds (at least for the time being), ending the week lower by 0.8 points, at 5% (after briefly falling below 5% to 4.97% on Thursday) down from last week’s close of 5.08%. The Mannarino Risk Index declined 5 points to 316, vs last week’s 321, but remains firmly in the mid-Extreme Risk level (max is 350), as it has closed over 300 for the 7th straight week. With the Mid-term Elections just around the corner, conditions are expected to remain uncertain.
The VIX (market volatility), bounced around all week, ultimately falling 1.1 points, to 19.4 vs last weeks close of 20.5, with daily fluctuations. As we often note, any break-through of the crucial “20” mark suggests a pullback.
Economic reports this week focused on earnings and very weak Real Estate reports, including Pending Home Sales, Housing Starts/Building Permits, and Mortgage Applications, all of which are down significantly Year-over-Year. This comes as no surprise with the rise in interest rates, and another hike expected before year’s end.
Astrologically, we have now entered Scorpio season (Oct 23 – Nov 21), signifying sharper, Mars led aggressive energies, signifying stronger rallies, or drops, in equity price action. Libra season ended on Thursday (Oct 22), and, as noted, Libra signifies balance, fairness, and justice, which has recently emerged in the Equal-weight S&P (RSP), as broader strength has occurred. Major uncertainty and nervousness persist in market conditions, which caused the expected spike in volatility. Please review our Sign Language – Scorpio blog, dated 10-8-26 for more details.
As discussed in recent weeks, current shorter-term transits/aspects of note include the ongoing Venus Retrograde (Oct 3 – Nov 14), whose energies finally kicked in last week, and the Mercury Retrograde beginning this weekend (Oct 24 – Nov 15), which are both traditionally negative for the markets. Both retrogrades will last through the Mid-Term Elections, another historical volatile time frame, during which tighter stop-losses and lower share sizes are suggested. Please review our Did You Know – About the Mid-Term Elections blog, dated 9-23-26, for more details.
Longer-term, the planet Jupiter remains in the sign of Leo until July 26, 2027, highlighting fashion, self-pleasing products, creativity, and travel (signified by the Consumer Discretionary sector), as well as leadership, defense, and gold (Please refer to our Trader Transits – Jupiter in Leo blog, dated 6-12-26, for further information). Consumer Discretionary stocks, that usually rally in the holiday shopping period, have stalled with recent low Consumer Sentiment and Confidence readings, as well as rising interest rates. Keep in mind that travel-related stocks have slumped due to their sensitivity to oil prices, which are vulnerable to the military conflict status (or “perceived” status).
Also, as discussed heavily in recent months, Uranus (sudden, unexpected events/high technology) will remain in the sign of Gemini (communications, transportation, advanced technology) until 2033. Uranus’ energies have continued since the end of May, when Uranus entered the sign, with unexpected reversals in both directions (especially with technology), as the market remains choppy and cannot seem to make up its mind (Gemini). Please also review our Trader Transits – Uranus in Gemini blog, dated 3-30-26.
As we have noted for over 1 year now, sectors of the technology industry that are likely to continue their advance into the future include AI, robotics, quantum computing, and space development, with Pluto positioned in Aquarius, and Uranus in Gemini, for many years to come, though they will experience pullbacks (sometimes sizeable) along the way.
Gold (ruled by the Sun), and Silver (ruled by the Moon), continued their weakness, hitting 3-month lows, as the U.S. Dollar remains strong with higher interest rates. The Gold to Silver Ratio rose slightly to 74.1, up 1.1 points from last week’s close of 73, its highest reading in 10 months. The level remains rather neutral, though would be favoring silver if it continues to rise. As we continue to stress, both metals remain good buys after pullbacks, so long as central banks continue to buy, which they are, and Safe-Haven investments remain popular, which is expected. However, there may be a further pullback if the additional rate hike occurs.
Finally, Bitcoin (ruled by Uranus), continues to consolidate at the low end of its range, as volume remains low. Its Fear & Greed Index remains in the Neutral level, though it continues to slip, ending the week 3 points lower, at 46, after closing last week at 49. No current catalyst is present for crypto, as the recently discussed Clarity Act has stalled in the Senate and still awaits the next step. Please review our Did You Know? – About The Clarity Act blog, dated 7-26-26, for further information.
***As always, this information is not intended to be financial advice, or any specific buy or sell recommendation, but rather a guide to assist the reader in some further understanding of current economic conditions/movements in the sky, and how they can affect moods, behaviors, world events, and financial markets.