FEAR & GREED INDEX 33
Weekly Update
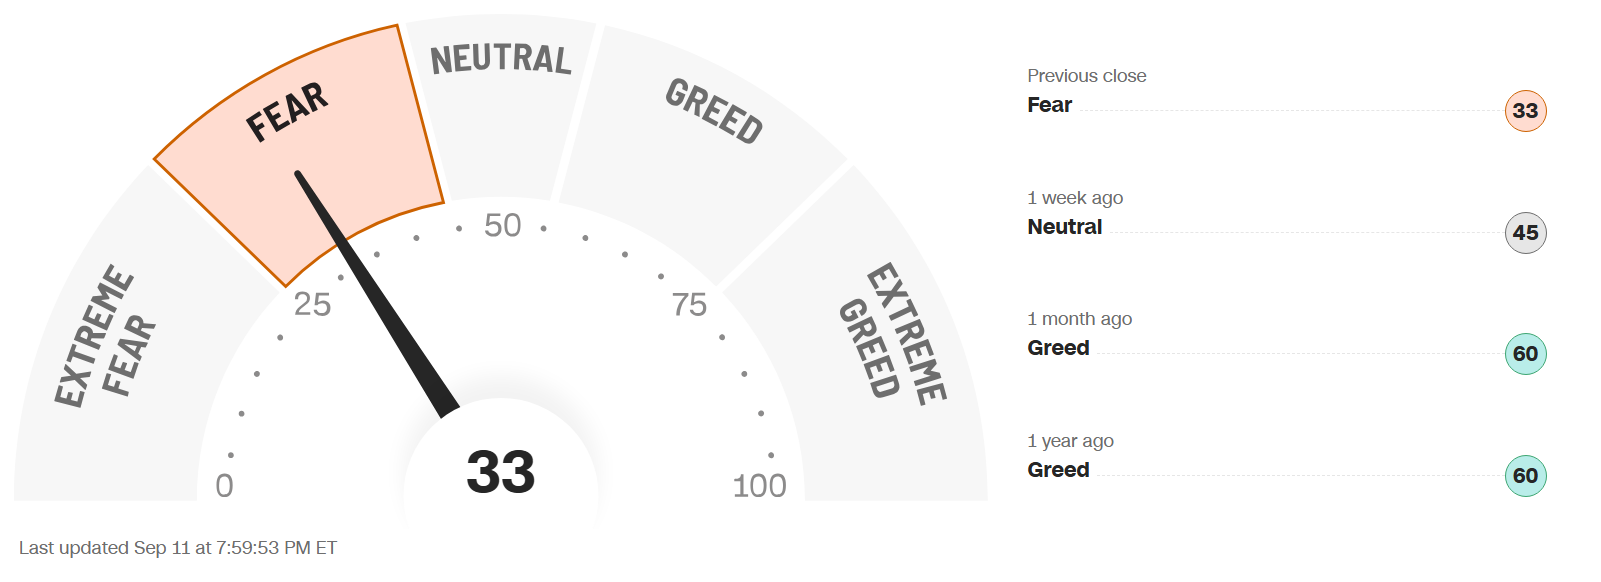
The Fear & Greed Index (found on cnn.com) is one of the easiest indicators to use to determine current market emotion. This simple to read gauge, highlighted in our publication When to Buy and When to Sell: Combining Easy Indicators, Charts, and Financial Astrology (available on Amazon), is measured in a range from 0-100, and currently reads 33 as of the close on Friday, September 11, 2026.
The gauge fell deeper into the Fear category, dropping 9 points from last week’s close of 42. This was reflected in the S&P 500, which slipped 60 points, from 7,718 to 7,658, but was much worse before Friday’s 65-point rally.
The 7 internal factors used to formulate this gauge are listed on the screen (below):
Market Momentum – (S&P 500 vs its 125-day moving avg) = FEAR
Market Volatility (measured by the VIX) = NEUTRAL
Put to Call Ratio 5-day avg. (# of Puts (bearish) vs Calls (bullish) = FEAR
Stock Price Strength (# of new 52-week highs vs new 52-week lows) = EXTREME FEAR
Stock Price Breadth (# of shares rising vs falling on NYSE) = EXTREME FEAR
Safe-Haven Demand (which measures stocks vs bonds) = FEAR
Junk Bond Demand (non-govt. bond yield spread) = GREED
This week, 3 of these 7 factors changed levels, as momentum categories remain low. Both Stock Price Breadth and the Put to Call Ratio slipped back into Fear levels, joining the other momentum factors, suggesting all is not well with the underlying structure of the markets. Overall, the market appears very fragile as we navigate through a weak seasonal period.
Moving Averages’ (MAs) bullish sentiment continued downward this week, with the longer-term 200-days now only at 51% (vs last week’s close of 57%), with the DJIA still leading at 67%. The shorter-term MAs fell to 39% on the 50-day (vs 50% last week), and to 30% on the 20-day (vs 45% last week). Sector strength was very fragmented again this week, as most declined, though recent leader Energy reversed upward again with rising oil prices, and Financials and Healthcare remained steady. Recent laggard, Utilities, dropped back again after a one-week reprieve.
The “Risk-On” sentiment also decreased as the market remains skittish with declining bonds/higher yields. Stubborn 10-yr bond yields remain elevated, rising 2.1 points, to 4.97%, from last week’s close of 4.78%, as interest rates remain at 19-year highs, which heeds caution. The Mannarino Risk Index (highlighted in our monthly Indicator Insights review), now reads 306, which reflects Extreme Risk, closing over 300 for the first time in 18 months. The VIX (market volatility) crept higher all week, until Friday’s rally, still closing up 1.3 points, at 15.8 vs last weeks close of 14.5. The low summer trading volume has begun to pick up, as it usually does after Labor Day. As we often note, however, any break-through of the crucial “20” mark suggests a pullback.
Economic reports this week focused on inflation data, including the Producer’s Price Index (PPI), reported on Thursday, which was higher than expected, and the Consumer’s Price Index (CPI), reported on Friday, which was in-line at 3.4%. Consumer Sentiment also declined and was again lower than expected.
Astrologically, Virgo season continues through Sept 22. Virgo season is typically weak in the markets, with low confidence, a conservative approach, and higher volatility, as traders return from summer vacations. Trading volume normally increases, and there are few catalysts after earnings season is complete. The last 2 years have been positive, however, bucking the trend of the past few decades. Major uncertainty persists in current market conditions, despite recent highs, which is not expected to change anytime soon, so proceed with caution. Please review our Sign Language – Virgo blog, dated 8-8-26 for more details.
Current shorter-term transits/aspects of note include the planet Venus, which now entered the sign of Scorpio (Sept 10 – Oct 25) signifying increased volatility from the calmer Libra. The planet Mercury also changed signs on the same day, from Virgo to Libra (Sept 10 – Sept 30), signifying more balance and less harsh judgments. The communications sector has risen during this time frame, especially since Mercury formed a conjunction with the Sun on August 27.
Longer-term, the planet Jupiter remains in the sign of Leo until July 26, 2027, highlighting fashion, self-pleasing products, creativity, and travel (signified by the Consumer Discretionary sector), as well as leadership, defense, and gold (Please refer to our Trader Transits – Jupiter in Leo blog, dated 6-12-26, for further information). Stocks in those sectors (especially defense and gold) have shown some improvement, as expected, though discretionary stocks have stalled with recent low Consumer Sentiment and Confidence readings. Keep in mind that travel-related stocks have slumped due to their sensitivity to oil prices, which are vulnerable to the military conflict status (or “perceived” status). Also, as discussed heavily in recent months, Uranus (sudden, unexpected events/high technology) will remain in the sign of Gemini (communications, transportation, advanced technology) until 2033.
Uranus turned retrograde as well on Thursday, Sept 10 (lasting through Feb 8, 2027), as explained in last week’s Planet Power – Uranus Retrograde blog, dated 9-3-26. Uranus’ energies continue, with quick, unexpected reversals, in both directions, as the market remains choppy and cannot seem to make up its mind (Gemini). This “divergence” is expected to continue in the short-term, as we’ve expressed in the past several weeks. Please also review our Trader Transits – Uranus in Gemini blog, dated 3-30-26.
As we have noted for over 1 year now, sectors of the technology industry that are likely to continue their advance into the future include AI, robotics, quantum computing, and space development, with both Pluto positioned in Aquarius, and Uranus in Gemini, for many years to come, though they will experience pullbacks (sometimes sizeable) along the way.
Gold (ruled by the Sun), and Silver (ruled by the Moon), drifted downward throughout the week, as strength in the U.S. Dollar rose slightly. The Gold to Silver Ratio closed at 67.4, rising by 0.5 points from last week’s close of 66.9, as both metals continue to move together evenly, with no real bias toward either one. As we continue to stress, both metals remain good buys after pullbacks, so long as central banks continue to buy, which they are, and Safe-Haven investments remain popular, which is expected.
Finally, Bitcoin (ruled by Uranus), after a recent surge, has cooled down, drifting slightly lower with decreasing volume. Its Fear & Greed Index remained at the Greed level, though it did drop to 68, after closing the last 2 weeks at 77. The Clarity Act, a bill designed to regulate the cryptocurrency and blockchain spaces in the U.S., may also help to boost the sector, after advancing through the committee on Friday, July 24, though it continues to await Senate approval. Please see our Did You Know? – About The Clarity Act blog, dated 7-26-26, for further information.
***As always, this information is not intended to be financial advice, or any specific buy or sell recommendation, but rather a guide to assist the reader in some further understanding of current economic conditions/movements in the sky, and how they can affect moods, behaviors, world events, and financial markets.