FEAR & GREED INDEX 29
Weekly Update
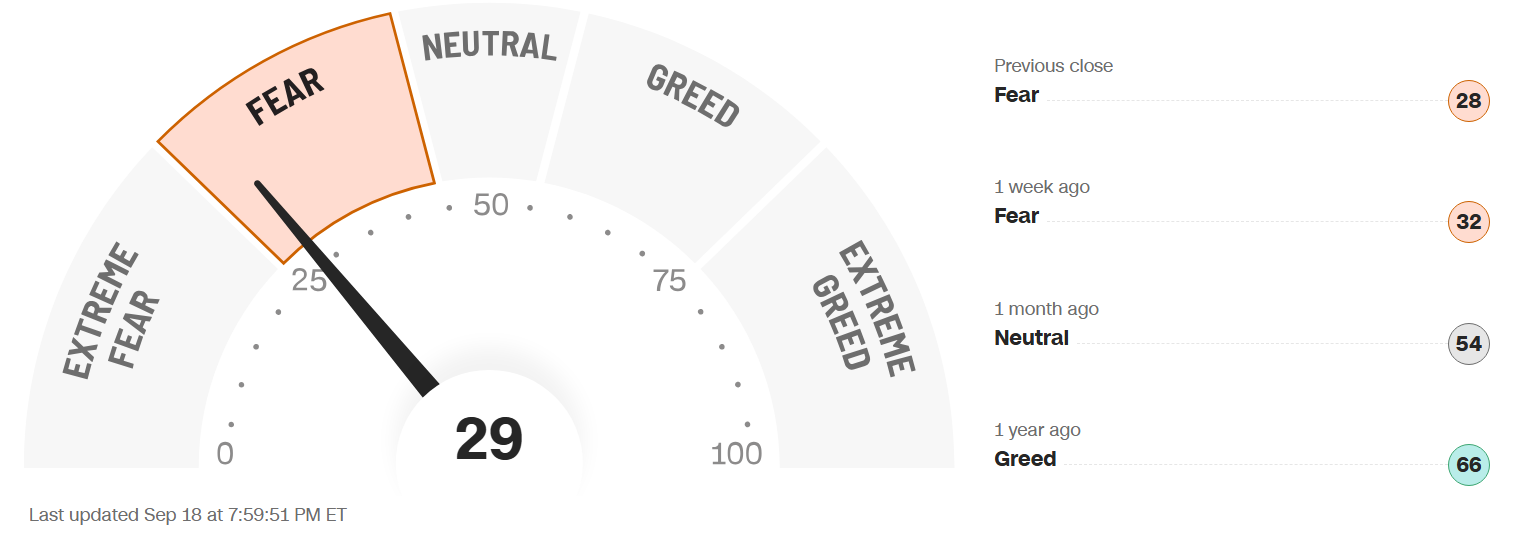
The Fear & Greed Index (found on cnn.com) is one of the easiest indicators to use to determine current market emotion. This simple to read gauge, highlighted in our publication When to Buy and When to Sell: Combining Easy Indicators, Charts, and Financial Astrology (available on Amazon), is measured in a range from 0-100, and currently reads 29 as of the close on Friday, September 18, 2026.
The gauge fell deeper into the Fear category this week, dropping 4 more points from last week’s close of 33. This was reflected in the S&P 500, which declined only 8 points, from 7,658 to 7,650, after rallying on Thursday and Friday.
The 7 internal factors used to formulate this gauge are listed on the screen (below):
Market Momentum – (S&P 500 vs its 125-day moving avg) = FEAR
Market Volatility (measured by the VIX) = NEUTRAL
Put to Call Ratio 5-day avg. (# of Puts (bearish) vs Calls (bullish) = FEAR
Stock Price Strength (# of new 52-week highs vs new 52-week lows) = EXTREME FEAR
Stock Price Breadth (# of shares rising vs falling on NYSE) = EXTREME FEAR
Safe-Haven Demand (which measures stocks vs bonds) = FEAR
Junk Bond Demand (non-govt. bond yield spread) = NEUTRAL
This week, only 1 of these 7 factors changed levels, as sentiment in all momentum categories remain low, suggesting all remains fragile with the underlying structure of the markets in this seasonally weak period. Only Junk Bond Demand changed, from Greed to Neutral, as all bonds have decreased equally.
Moving Averages’ (MAs) bullish sentiment officially turned to bear this week, with the longer-term 200-days now at 48% (vs last week’s close of 51%), with the DJIA still leading at 60%, down from 67%. The shorter-term MAs declined to 34% on the 50-day (vs 39% last week), and to 27% on the 20-day (vs 30% last week). Sector strength was very fragmented again this week, as most continued to decline, with Energy, Financials and Healthcare remaining steady. Infotech was actually the strongest short-term, while Utilities and Consumer Discretionary are the biggest laggards.
The “Risk-On” sentiment remains skittish with declining bonds/higher yields, as the Federal Reserve raised interest rates .25% at Wednesday’s meeting. Stubborn 10-yr bond yields remain elevated, rising 0.3 points, to 5%, from last week’s close of 4.97%. This is the first time rates have breached the 5% mark since October of 2023, and only the second since 2007, just prior to the Global Financial Crisis. The Mannarino Risk Index (highlighted in our monthly Indicator Insights review), continued to climb, now reading 311, vs last week’s 306, which reflects Extreme Risk, closing over 300 for the first time in 18 months, for the 2nd straight week. The VIX (market volatility) surprisingly dropped this week, closing 1 point lower, at 14.8 vs last weeks close of 15.8. The low summer trading volume has begun to pick up, as it usually does after Labor Day, and volatility normally follows. As we often note, however, any break-through of the crucial “20” mark suggests a pullback.
Economic reports this week focused on housing, which was mixed, with little significant activity, and retail sales, which improved slightly. The Leading Indicator Index (LEI) fell 0.1%, to 95.5, it’s first decline since March as well. Neither had much of an impact, however, as the Fed’s rate hike took center stage.
Astrologically, Virgo season continues only until Tuesday (Sept 22), as Libra season begins on Wednesday, September 23, lasting through October 22, 2026. As noted, Virgo season is typically weak in the markets, with low confidence, a conservative approach, and higher volatility, as traders return from summer vacations. Virgo season is also less broad, and more selective, which has been reflected by the declining RSP (equal weighted SPY), as the MAGS have once again taken the lead in holding up the overall market. This year, with 2 trading days remaining, Virgo season has been mainly flat, with the S&P 500 losing 24 points. Libra signifies balance, fairness, and justice, though the market itself is mainly based on emotion and sentiment. Currently, major uncertainty persists in market conditions, despite recent highs, which is not expected to change anytime soon, so proceed with caution. Please review our Sign Language – Libra blog, dated 9-8-26 for more details.
Current shorter-term transits/aspects of note include the planet Venus, which has now entered the sign of Scorpio (Sept 10 – Oct 25) signifying increased volatility from the calmer Libra. A looming Venus Retrograde period, beginning October 3rd, traditionally negative for the markets, is quickly approaching. The planet Mercury also changed signs on the same day, from Virgo to Libra (Sept 10 – Sept 30), signifying more balance and less harsh judgments. The communications sector has risen during this time frame, especially since Mercury formed a conjunction with the Sun on August 27. However, there will also be another Mercury Retrograde period (also very challenging for the markets, beginning October 24. Both retrogrades will last through the Mid-Term Elections, and end in mid-November. Please review our upcoming Did You Know blog, later this week, for more details.
Longer-term, the planet Jupiter remains in the sign of Leo until July 26, 2027, highlighting fashion, self-pleasing products, creativity, and travel (signified by the Consumer Discretionary sector), as well as leadership, defense, and gold (Please refer to our Trader Transits – Jupiter in Leo blog, dated 6-12-26, for further information). Stocks in those sectors (especially defense and gold) have shown some improvement, as expected, though discretionary stocks have stalled with recent low Consumer Sentiment and Confidence readings. Keep in mind that travel-related stocks have slumped due to their sensitivity to oil prices, which are vulnerable to the military conflict status (or “perceived” status). Also, as discussed heavily in recent months, Uranus (sudden, unexpected events/high technology) will remain in the sign of Gemini (communications, transportation, advanced technology) until 2033.
The recent Uranus retrograde (Sept 10 - Feb 8, 2027), as explained in our recent Planet Power – Uranus Retrograde blog, dated 9-3-26, does not usually affect the market negatively. Uranus’ energies do continue, with quick, unexpected reversals, in both directions, however, as the market remains choppy and cannot seem to make up its mind (Gemini). This “divergence” is expected to continue in the short-term, as we’ve expressed in the past several weeks. Please also review our Trader Transits – Uranus in Gemini blog, dated 3-30-26.
As we have noted for over 1 year now, sectors of the technology industry that are likely to continue their advance into the future include AI, robotics, quantum computing, and space development, with both Pluto positioned in Aquarius, and Uranus in Gemini, for many years to come, though they will experience pullbacks (sometimes sizeable) along the way.
Gold (ruled by the Sun), and Silver (ruled by the Moon), rose this week, but were very volatile, as a result of the interest rate hike causing further strength in the U.S. Dollar. The Gold to Silver Ratio closed at 66.1, down 1.3 points from last week’s close of 67.4, as both metals continue to move together evenly, with no real bias toward either one. As we continue to stress, both metals remain good buys after pullbacks, so long as central banks continue to buy, which they are, and Safe-Haven investments remain popular, which is expected.
Finally, Bitcoin (ruled by Uranus), spiked on Friday, after a 1-month consolidation, though volume remains very low. Its Fear & Greed Index remained at the Greed level, ending the week 5 points higher, at 73, after closing last week at 68. The Clarity Act, a bill designed to regulate the cryptocurrency and blockchain spaces in the U.S., which was helping to boost the sector, after advancing through the committee on Friday, July 24, did NOT receive Senate approval this week, and awaits the next step. Please see our Did You Know? – About The Clarity Act blog, dated 7-26-26, for further information.
***As always, this information is not intended to be financial advice, or any specific buy or sell recommendation, but rather a guide to assist the reader in some further understanding of current economic conditions/movements in the sky, and how they can affect moods, behaviors, world events, and financial markets.