FEAR & GREED INDEX 45
Weekly Update
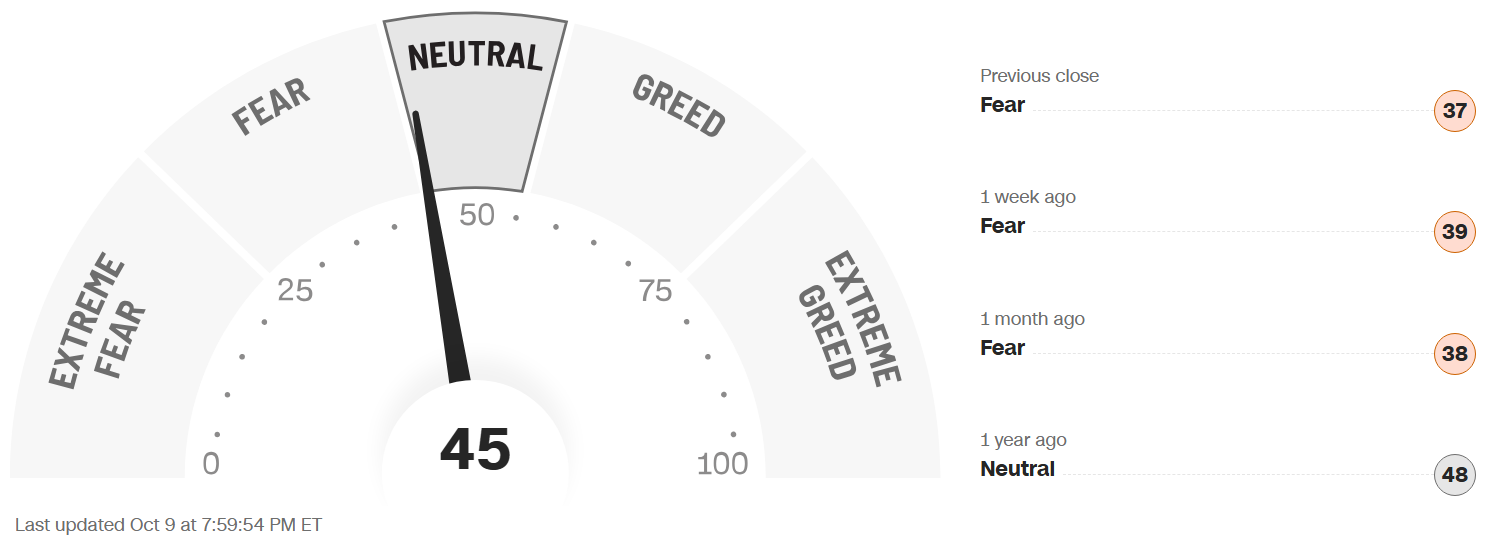
The Fear & Greed Index (found on cnn.com) is one of the easiest indicators to use to determine current market emotion. This simple to read gauge, highlighted in our publication When to Buy and When to Sell: Combining Easy Indicators, Charts, and Financial Astrology (available on Amazon), is measured in a range from 0-100, and currently reads 45 as of the close on Friday, October 9, 2026.
The gauge edged back into the Neutral category this week, for the first time in 5 weeks, rising 8 points from last week’s close of 37. This was reflected in the S&P 500, which gained 90 points, from 7,721 to 7,811, as the market was positive 3 out of 5 days, including Friday.
The 7 internal factors used to formulate this gauge are listed on the screen (below):
Market Momentum – (S&P 500 vs its 125-day moving avg) = GREED
Stock Price Strength (# of new 52-week highs vs new 52-week lows) = EXTREME FEAR
Stock Price Breadth (# of shares rising vs falling on NYSE) = EXTREME FEAR
Market Volatility (measured by the VIX) = NEUTRAL
Put to Call Ratio 5-day avg. (# of Puts (bearish) vs Calls (bullish) = FEAR
Safe-Haven Demand (which measures stocks vs bonds) = GREED
Junk Bond Demand (non-govt. bond yield spread) = EXTREME GREED
This week, 3 of these 7 factors changed levels, as overall momentum increased, though internals (strength and breadth) remain low, reflecting the continued fragile underlying structure of the markets in this seasonally weak period. Safe Haven and Junk Bond demand spiked, however, an indicator of defensive positioning by institutions.
Market internals momentum Moving Averages’ (MAs) bearish sentiment continued, with the longer-term 200-days in an official “bear” market (under 50%), even at 43% (vs last week’s close of 43%), with the DJIA still leading at 60%, (same as week). The shorter-term MAs were also even at 28% on the 50-day (vs 28% last week), but rose to 38% on the 20-day (vs 30% last week), with the uptick this week. Sector strength remained very fragmented once again this week, as Infotech, Healthcare, and Energy remained strong in the short-term. A “Red-Alert” was recently sent by the Financials as not a single stock is trading over its 20-day MA, and only 3% over their 50-days last week. The beginning of earnings season next week kicks in, with the important Financials in the spotlight.
The “Risk-On” sentiment remains sketchy, as uncertainty regarding the military conflict and rising interest rates continue to control the market. 10-yr bond yields remain elevated, as they have for several weeks, ending the week down just 0.3 points, at 5.24%, from last week’s close of 5.27%. Bond yields remain well over the 5% mark for the first time since October of 2023, and only the second time since 2007, just prior to the Global Financial Crisis. This level is reflected in the Mannarino Risk Index (highlighted in our monthly Indicator Insights review), which remained about even, declining by only 1 point, and now reads 333, vs last week’s 334. This gauge continues to remain firmly in the mid-Extreme Risk level (max is 350), as it closed over 300 (for the first time in 18 months) for the 4th straight week. Despite being near all-time highs, markets are very nervous with the looming Global Debt Crisis, and is still being heavily led by the tech sector, especially the MAGS.
The VIX (market volatility), declined 0.5 points, to 14.8 vs last weeks close of 15.3, remaining surprisingly low for this time of year. As we often note, however, any break-through of the crucial “20” mark suggests a pullback.
Economic reports this week were very light, with the most significant reports consumer-related. Consumer Credit was higher (more debt), and Consumer Sentiment down again from last month, while decreasing 13% from October of 2025. This has been reflected with declining consumer-related stocks for months, with hopes of some improvement in the upcoming holiday shopping season. Another rate hike, however, would not be favorable for these statistics.
Astrologically, we are nearing the end of Libra season (Sept 23 - Oct 22). As noted, Libra signifies balance, fairness, and justice, though the market itself is mainly based on emotion and sentiment. Currently, major uncertainty and nervousness persist in market conditions, despite recent highs, which is not expected to change anytime soon, so proceed with caution. Please review our Sign Language – Libra blog, dated 9-8-26 for more details.
As noted in recent weeks, current shorter-term transits/aspects of note include the Venus Retrograde (Oct 3 – Nov 14), and the upcoming Mercury Retrograde (Oct 24 – Nov 15), which are both traditionally negative for the markets. Both retrogrades will last through the Mid-Term Elections, another historical volatile time frame. Please review our Did You Know – About the Mid-Term Elections blog, dated 9-23-26, for more details.
Longer-term, the planet Jupiter remains in the sign of Leo until July 26, 2027, highlighting fashion, self-pleasing products, creativity, and travel (signified by the Consumer Discretionary sector), as well as leadership, defense, and gold (Please refer to our Trader Transits – Jupiter in Leo blog, dated 6-12-26, for further information). Consumer Discretionary stocks, that usually rally in the holiday shopping period, have stalled with recent low Consumer Sentiment and Confidence readings, as well as rising interest rates. Keep in mind that travel-related stocks have slumped due to their sensitivity to oil prices, which are vulnerable to the military conflict status (or “perceived” status).
Also, as discussed heavily in recent months, Uranus (sudden, unexpected events/high technology) will remain in the sign of Gemini (communications, transportation, advanced technology) until 2033. The current Uranus retrograde (Sept 10 - Feb 8, 2027), as explained in our recent Planet Power – Uranus Retrograde blog, dated 9-3-26, does not usually affect the market negatively overall. Uranus’ energies do continue, however, with quick, unexpected reversals, in both directions, as the market remains choppy and cannot seem to make up its mind (Gemini). This “divergence” is expected to continue in the short-term, as we’ve expressed in the past several weeks. Please also review our Trader Transits – Uranus in Gemini blog, dated 3-30-26.
As we have noted for over 1 year now, sectors of the technology industry that are likely to continue their advance into the future include AI, robotics, quantum computing, and space development, with both Pluto positioned in Aquarius, and Uranus in Gemini, for many years to come, though they will experience pullbacks (sometimes sizeable) along the way.
Gold (ruled by the Sun), and Silver (ruled by the Moon), were volatile this week, as the U.S. Dollar remains strong with the recent interest rate hike, and another forecast before the end of the year, though it did close slightly higher. The Gold to Silver Ratio barley changed, closing at 68.9, down just 0.4 points from last week’s close of 68.5, but remains neutral as both metals continue to move together evenly, with no real bias toward either one. As we continue to stress, both metals remain good buys after pullbacks, so long as central banks continue to buy, which they are, and Safe-Haven investments remain popular, which is expected. However, there may be a further pullback if the additional rate hike occurs.
Finally, Bitcoin (ruled by Uranus), cooled off considerably this week as volume remains very low. Its Fear & Greed Index dropped to the Neutral level, ending the week at 55, after closing last week at 67. The recently discussed Clarity Act has stalled in the Senate, and awaits the next step. Please review our Did You Know? – About The Clarity Act blog, dated 7-26-26, for further information.
***As always, this information is not intended to be financial advice, or any specific buy or sell recommendation, but rather a guide to assist the reader in some further understanding of current economic conditions/movements in the sky, and how they can affect moods, behaviors, world events, and financial markets.